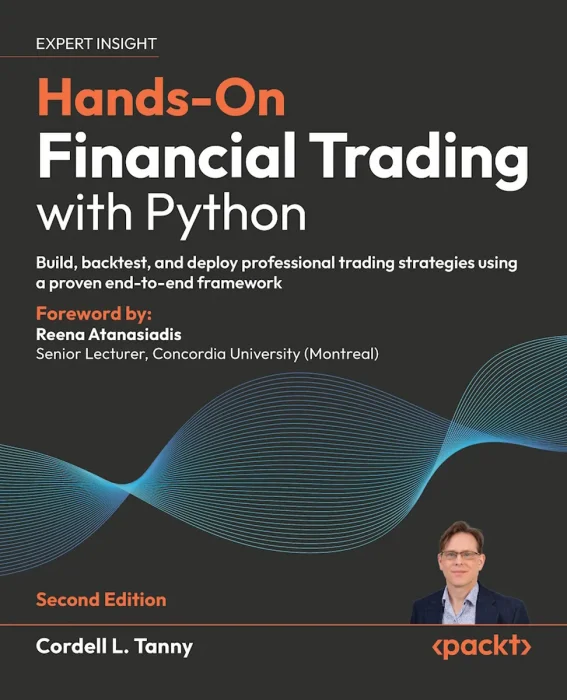
Hands-On Financial Trading with Python
Published October 30th, 2026
ISBN 1806664453
Language English
Pages 232
Formats EPUB
Add favorites
Learn algorithmic trading with Python by building one complete strategy, from market data to automated execution. Explore machine learning, AI signals, and rigorous backtesting
Key Features
• Follow one volatility tail-hedge strategy from market data to cloud deployment, and build more that show a real edge
• Explore time-series models, machine learning, and AI-driven alpha signal generation
• Challenge backtests with walk-forward analysis and detect lookahead bias and overfitting
Book Description
Go beyond learning Python libraries in isolation. This book teaches you the complete workflow professionals use to build systematic trading strategies.
You start by acquiring, exploring, and cleaning market data, handling missing values, misaligned time series, and noise. From there, you form trading hypotheses, generate signals, and define entry and exit rules. You evaluate risk-adjusted performance and challenge your backtests through out-of-sample testing and walk-forward analysis. Next, you explore time-series models, machine learning for trading, and AI-driven alpha signal generation. Finally, you build a deployable strategy repository and automate execution in the cloud. One volatility tail-hedge strategy runs from raw data to cloud deployment, and you build five further strategies from published research, covering momentum, regime detection, economic indicators, and sector rotation, each tested to confirm that its signal does real work.
Drawing on 25 years of institutional trading experience, the book shows you how to spot lookahead bias and overfitting and distinguish promising signals from noise. You work with VectorBT and QuantStats, with PythonAnywhere for deployment. The book includes all the code, and by the end you have working strategies and a repeatable framework for algorithmic trading with Python
What you will learn
• Acquire, clean, and denoise financial time-series data
• Use exploratory analysis to develop trading hypotheses
• Build momentum, mean-reversion, and time-series strategies
• Apply machine learning and AI to alpha signal generation
• Validate backtests with out-of-sample and walk-forward testing
• Detect lookahead bias, survivorship bias, and overfitting
• Evaluate strategies using risk-adjusted performance metrics
• Build a deployable repository and automate cloud execution
Who this book is for
This book is for traders going systematic, data scientists entering quantitative finance, and portfolio managers automating their workflows. Whether you are building your first complete strategy or moving beyond isolated Python scripts, you share one frustration: books that teach tools but not how to put them together. This book gives you that missing piece.
You should be comfortable with basic Python, including functions, loops, and working in Jupyter notebooks, and with finance fundamentals such as returns, volatility, and risk.
Download Hands-On Financial Trading with Python
Similar books


Information
Users of Guests are not allowed to comment this publication.
Users of Guests are not allowed to comment this publication.